Refine
Estimated Years 2000-2009Clear
18,679 results foundRefine Search
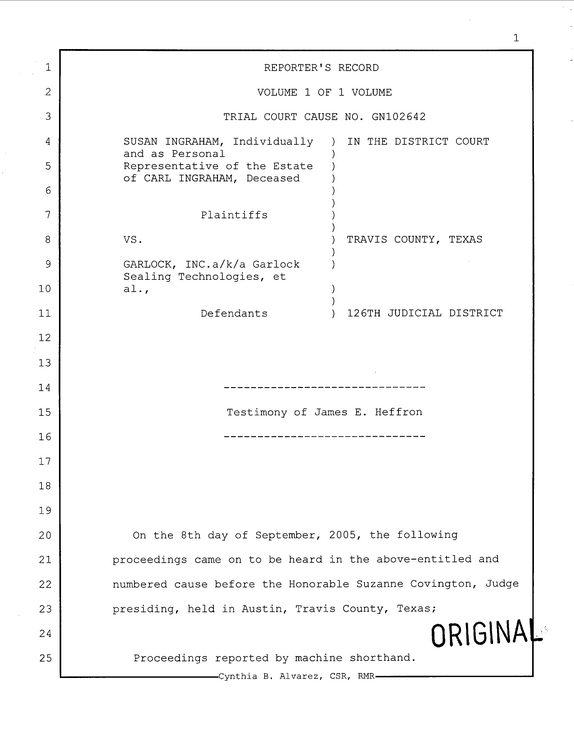
1 1 REPORTER'S RECORD 2 VOLUME 1 OF 1 VOLUME 3 TRIAL COURT CAUSE NO.
refid# XRQJ1anLZkYJ7DX5LznqD4k0498 pages
file:///J|/Imports/riddarh1_020602.txt file:///J|/Imports/riddarh1_020602.txt (1 of 218) [4/5/2002 3:01:32 PM] file:///J|/Imports/riddarh1_020602.txt 1 1 IN THE DISTRICT COURT 2 298TH JUDICIAL DISTRICT 3 NO. 00-05448-M 4 5 ************** 6 CARY J.
refid# 3gZQkDpRBnnydekyeRZkx6G3218 pages
IN THE CIRCUIT COURT THIRD JUDICIAL CIRCUIT MADISON COUNTY, ILLINOIS JANE GUDMUNDSON, Individually and as Special Administrator of ) the Estate of HARVEY G. ) GUDMUNDSON, Deceased, ) ) No. 03-L-538 Plaintiff, ) ) vs. ) ) JOHN CRANE, INC., et al., ) ) Defendants. ) ) VIDEOTAPED EVIDENCE DEPOSITION OF ROLAND DOKTOR Taken on behalf of Plaintiff January 18, 2005 Certify Question: Page 114, Line 13 Sarah L.
refid# 9J6kNXL4abm2zM8jEJVJ6Xm7p72 pages
r,13 m3 ;> t- j nn fJT3ic?
refid# 0JQd4w91QXMkX6Eb6y0y499jb1 page
THE BENDIX CORPORATION MARSHALL ECLIPSE DIVISION TROY, NEW YORK K)Ku HTr< FIELD ACT UP P 0 LiOX 2003 LiVOwiA fol **6151 SHIPPED TO FORD MTR DLL VAL 0P SL'RV OPEft RTt 130 rr-.ur-rtni.
refid# 1gD0p14e7be73JEqr26nmVxNa1 page
Ill *rv. i:,6?
refid# mpY7w8eR20xbe6dKGRp5NoB301 page
THE BENDIX CORPORATION FRICTION MATERIALS DIVISION TROY, NEW YORK CLEVELAND, TENN, FOflO Tf4 FlEi-O ACT PCP H O UOK 2003 :V.
refid# 2RenZ4276BVBMp6R8QZm9NJma1 page
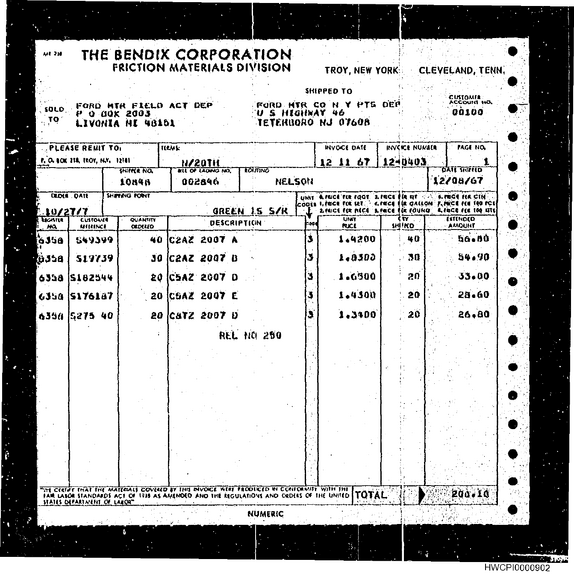
THE BENDIX CORPORATION FRICTION MATERIALS OlVlSION TROY, NEW YORK; FORD HTK FlCLP ACT DKP P O dOK 2004 LIVONIA Ml *818* SHIPPED TO ford htk co m Y PTS oef U S HfOtiWAY 46 TETKMaoAO MJ 0760ft CLEVELAND, TENN, CUSTOM'* ACCOUtO HO, 00100 PUEASE REMIT TOi !
refid# 7MqjEkKqQL60K8XvBZO59VB7o1 page
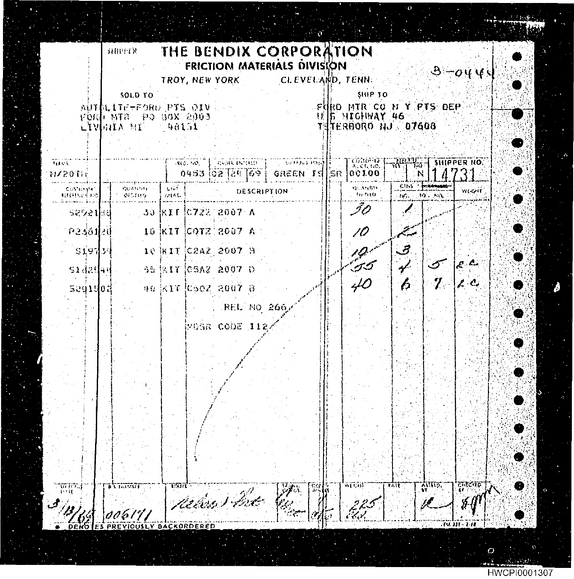
aHIl'HK THE BENDIX CORPORATION FRICTION MATERIALS DIVISION trov, New York ci.evEi.vyib, rewc 3 --OiLfXfs S01.0 TO Ai.lT >KtTt.'
refid# G5ppEJ8ok03B53NOd1NKb2Xdv1 page
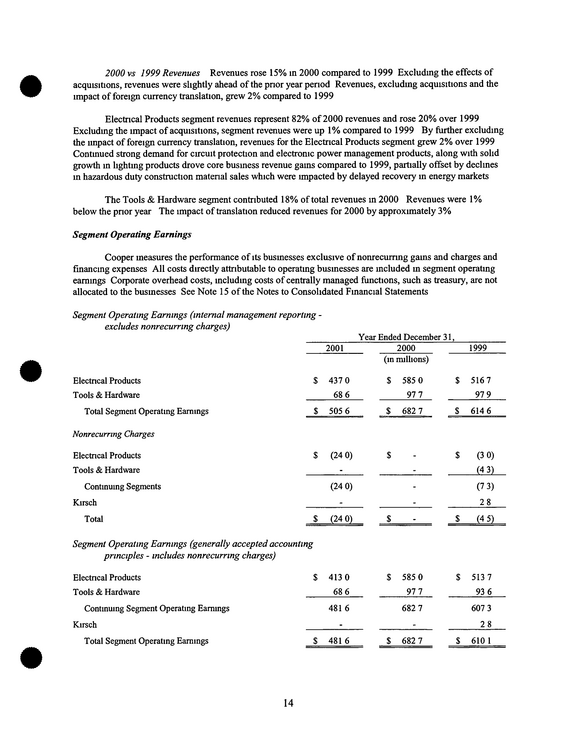
2000 vs 1999 Revenues Revenues rose 15% in 2000 compared to 1999 Excluding the effects of acquisitions, revenues were slightly ahead of the prior year period Revenues, excludmg acquisitions and the impact of foreign currency translation, grew 2% compared to 1999 Electrical Products segment revenues represent 82% of 2000 revenues and rose 20% over 1999 Excludmg the impact of acquisitions, segment revenues were up 1% compared to 1999 By further excluding the impact of foreign currency translation, revenues for the Electrical Products segment grew 2% over 1999 Contmued strong demand for circuit protection and electronic power management products, along with solid growth m lighting products drove core busmess revenue gams compared to 1999, partially offset by declines in hazardous duty construction material sales which were impacted by delayed recovery m energy markets The Tools & Hardware segment contributed 18% of total revenues m 2000 Revenues were 1% below the prior year The impact of translation reduced revenues for 2000 by approximately 3% Segment Operating Earnings Cooper measures the performance of its busmesses exclusive of nonrecurring gains and charges and financing expenses All costs directly attributable to operating busmesses are included m segment operating eammgs Corporate overhead costs, including costs of centrally managed functions, such as treasury, are not allocated to the busmesses See Note 15 of the Notes to Consolidated Financial Statements Segment Operating Earnings (internal management reporting excludes nonrecurring charges) 2001 Year Ended December 31, 2000 (in millions) 1999 Electrical Products Tools & Hardware Total Segment Operating Earnings $ 437 0 68 6 $ 505 6 $ 585 0 97 7 $ 682 7 $ 516 7 97 9 $ 614 6 Nonrecurring Charges Electrical Products Tools & Hardware Continuing Segments Kirsch Total $ (24 0) - (24 0) - $ (24 0) $ - $ $ (3 0) (4 3) (7 3) 28 $ (4 5) Segment Operating Earnings (generally accepted accounting principles - includes nonrecurring charges) Electncal Products Tools & Hardware Continuing Segment Operating Earnings Kirsch Total Segment Operating Eammgs $ 413 0 68 6 481 6 - $ 481 6 $ 585 0 97 7 682 7 - $ 682 7 $ 513 7 93 6 607 3 28 $ 6101 14
refid# VG44Bja64yjaY2Em28kwyDo0N1 page
COOPER INDUSTRIES LTD(Form 424B2, Received 10/25/2002 13 39 31) (GUARANTEED BY COOPER INDUSTRIES, LTD ) 5 50% SENIOR NOTES DUE 2009 [COOPER LOGO] PROSPECTUS SUPPLEMENT October 23, 2002 Joint Book-Running Managers SALOMON SMITH BARNEY UBS WARBURG BANC OF AMERICA SECURITIES LLC JPMORGAN PNC CAPITAL MARKETS, INC.
refid# repkzzvYQzQwzkGErzyyoGQMe1 page
FricSiem Materiats f Dvmnon.
refid# jgmRyVBwBxX95R7dRZ7YBa54Z1 page
-TfHwTot*.'. ' -Term. , Friction Materials Division --V- SW7o` ^TCtlTErFORO PtS;XV {?
refid# J3Qe7qggmG0n6zLqDv9ZDM3v1 page
elOvk Page 14 of 84 Table of Contents Federal-Mogul bankruptcy proceedings This included negotiations with the Representatives regarding participation in Federal-Mogul's proposed 524(g) asbestos trust Based on the status of the negotiations in 2004, Cooper concluded that it was probable that Federal-Mogul will reject the 1998 Agreement Cooper also concluded that the Representatives would require any negotiated settlement through the Federal-Mogul bankruptcy to be at the high end of the Bates White, LLC liability analysis and with substantially lower insurance recovery assumptions and higher administrative costs While Cooper believes that the insurance has significant additional value, extensive litigation with the insurance carriers may be required to receive recoveries and there is risk that court decisions could reduce the value of the recoveries Additionally, the assumptions on liability payments could prove inaccurate over time If Cooper is unable to reach a settlement with the Representatives and the 1998 Agreement is rejected, Cooper would be required to reflect an accrual for the total estimated liability and a receivable for the probable insurance recoveries Generally accepted accounting principles provide relatively conservative requirements for the recording of insurance recoveries and a substantial portion of the potential insurance recoveries would not be reflected as receivables until future events occur During late February and early March 2004, Cooper reassessed the accrual required based on the then current status of the negotiations with the Representatives and the liability and insurance receivable that would be required to be recorded if this matter is not settled within the Federal-Mogul bankruptcy Cooper concluded that resolution within the Federal-Mogul proposed 524(g) asbestos trust would likely be within the range of the liabilities, net of insurance recoveries, that Cooper would accrue if this matter were not settled within the Federal-Mogul bankruptcy Accordingly, Cooper recorded a $126 0 million after-tax discontinued operations charge, net of a $70 9 income tax benefit, in the fourth quarter of 2003 Cooper has continued discussions with the Representatives, but to date has been unable to reach a satisfactory conclusion At this time, the exact manner in which this issue will be resolved is not known The accrual for potential liabilities related to the Automotive Products sale and the Federal-Mogul bankruptcy was $225 1 million and $252 5 million at December 31, 2004 and 2003, respectively ITEM 4.
refid# x1ryKN9yJEdqLyQyjQpov1B9b1 page
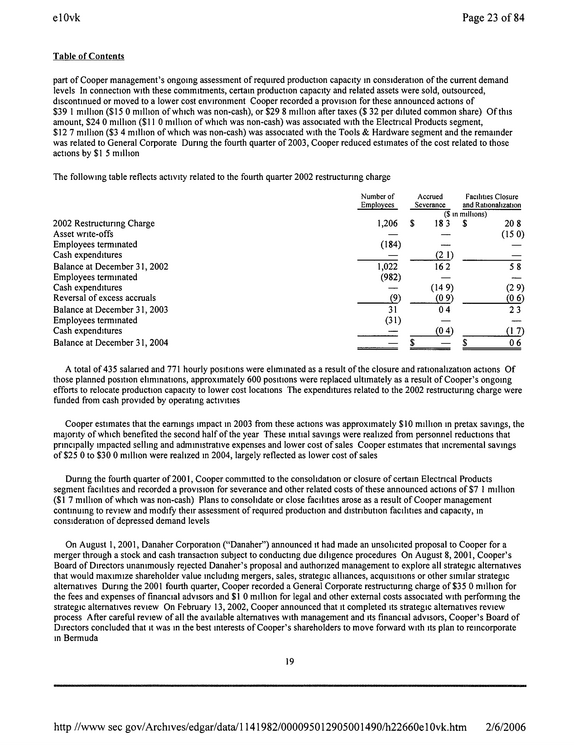
elOvk Page 23 of 84 Table of Contents part of Cooper management's ongoing assessment of required production capacity in consideration of the current demand levels In connection with these commitments, certain production capacity and related assets were sold, outsourced, discontinued or moved to a lower cost environment Cooper recorded a provision for these announced actions of $39 1 million ($15 0 million of which was non-cash), or $29 8 million after taxes ($ 32 per diluted common share) Of this amount, $24 0 million ($110 million of which was non-cash) was associated with the Electrical Products segment, $12 7 million ($3 4 million of which was non-cash) was associated with the Tools & Hardware segment and the remainder was related to General Corporate During the fourth quarter of 2003, Cooper reduced estimates of the cost related to those actions by $1 5 million The following table reflects activity related to the fourth quarter 2002 restructuring charge 2002 Restructuring Charge Asset write-offs Employees terminated Cash expenditures Balance at December 31, 2002 Employees terminated Cash expenditures Reversal of excess accruals Balance at December 31, 2003 Employees terminated Cash expenditures Balance at December 31, 2004 Number of Employees 1,206 -- (184) -- 1,022 (982) -- ________ 0 31 (31) -- -- Accrued Facilities Closure Severance and Rationalization ($ in millions) $ 183 $ 20 8 -- (15 0) -- (2 1) 162 -- (14 9) (0 9) 04 -- -- 58 -- (2 9) (0 6) 23 -- (0 4) $ --$ -- 0 7) 06 A total of 435 salaried and 771 hourly positions were eliminated as a result of the closure and rationalization actions Of those planned position eliminations, approximately 600 positions were replaced ultimately as a result of Cooper's ongoing efforts to relocate production capacity to lower cost locations The expenditures related to the 2002 restructuring charge were funded from cash provided by operating activities Cooper estimates that the earnings impact in 2003 from these actions was approximately $10 million in pretax savings, the majority of which benefited the second half of the year These initial savings were realized from personnel reductions that principally impacted selling and administrative expenses and lower cost of sales Cooper estimates that incremental savings of $25 0 to $30 0 million were realized in 2004, largely reflected as lower cost of sales During the fourth quarter of 2001, Cooper committed to the consolidation or closure of certain Electrical Products segment facilities and recorded a provision for severance and other related costs of these announced actions of $7 1 million ($1 7 million of which was non-cash) Plans to consolidate or close facilities arose as a result of Cooper management continuing to review and modify their assessment of required production and distribution facilities and capacity, in consideration of depressed demand levels On August 1, 2001, Danaher Corporation ("Danaher") announced it had made an unsolicited proposal to Cooper for a merger through a stock and cash transaction subject to conducting due diligence procedures On August 8, 2001, Cooper's Board of Directors unanimously rejected Danaher's proposal and authorized management to explore all strategic alternatives that would maximize shareholder value including mergers, sales, strategic alliances, acquisitions or other similar strategic alternatives During the 2001 fourth quarter, Cooper recorded a General Corporate restructuring charge of $35 0 million for the fees and expenses of financial advisors and $1 0 million for legal and other external costs associated with performing the strategic alternatives review On February 13, 2002, Cooper announced that it completed its strategic alternatives review process After careful review of all the available alternatives with management and its financial advisors, Cooper's Board of Directors concluded that it was in the best interests of Cooper's shareholders to move forward with its plan to reincorporate in Bermuda 19 http //www sec gov/Archives/edgar/data/1141982/000095012905001490/h22660el0vk.htm 2/6/2006
refid# zzXZXnJ8nY2oBvpVdOaEbwEbg1 page