Refine
Estimated Years 1990-1999Clear
5,222 results foundRefine Search
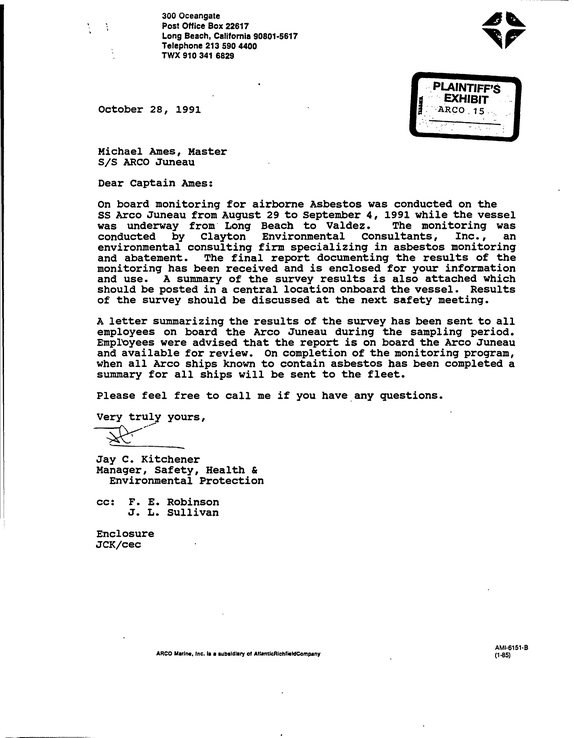
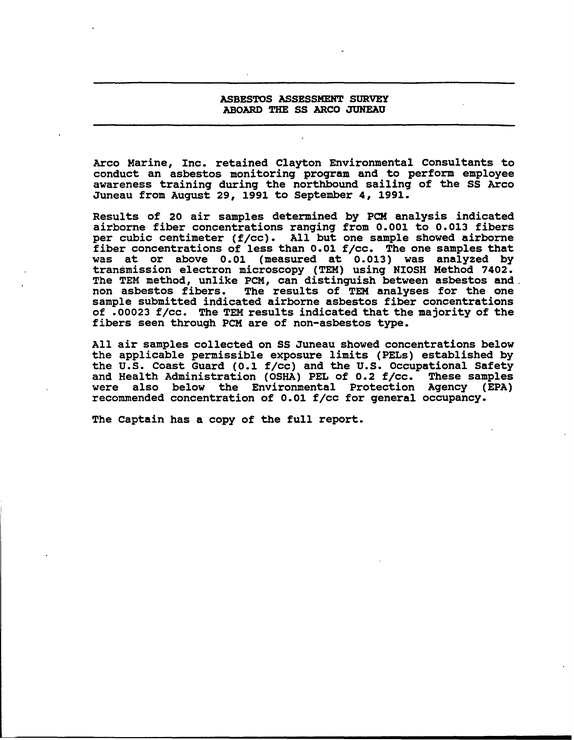
300 Oceangate Post Office Box 22617 Long Beach, California 90801-5617 Telephone 213 590 4400 TWX 910 341 6829 October 28, 1991 Michael Ames, Master S/S ARCO Juneau Dear Captain Ames: On board monitoring for airborne Asbestos was conducted on the SS Arco Juneau from August 29 to September 4, 1991 while the vessel was underway from Long Beach to Valdez.
refid# npbJp1XDzoE4e1zGpoyJ2N7xG2 pages
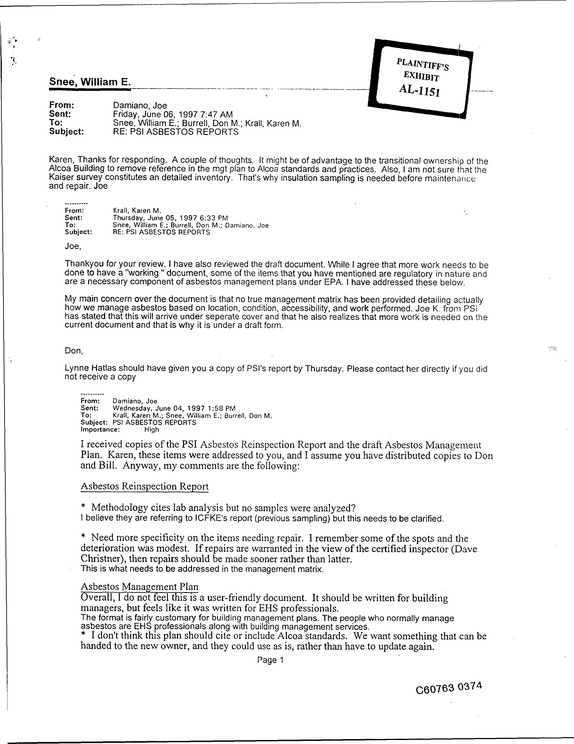
Snee, William E.
refid# ypOE28jy4jm4vMN0z0MN3MB7E2 pages
/ IN THE CIRCUIT COURT OF KANAWHA COUNTY, WEST VIRGINIA IN RE: ASBESTOS CIVIL ACTION NO. 92-C-8888 BEFORE: HONORABLE A.
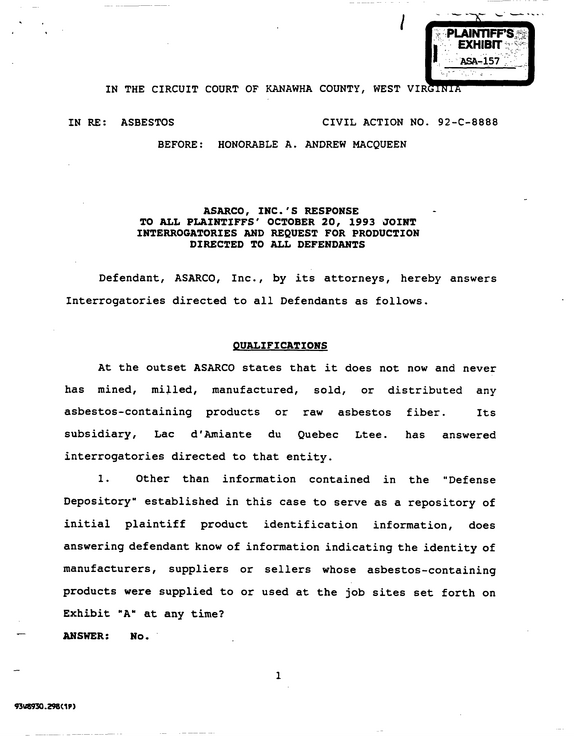
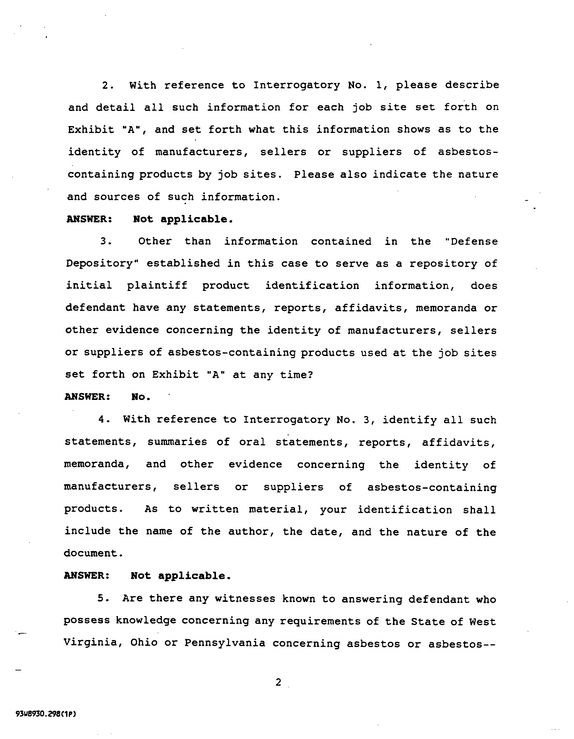
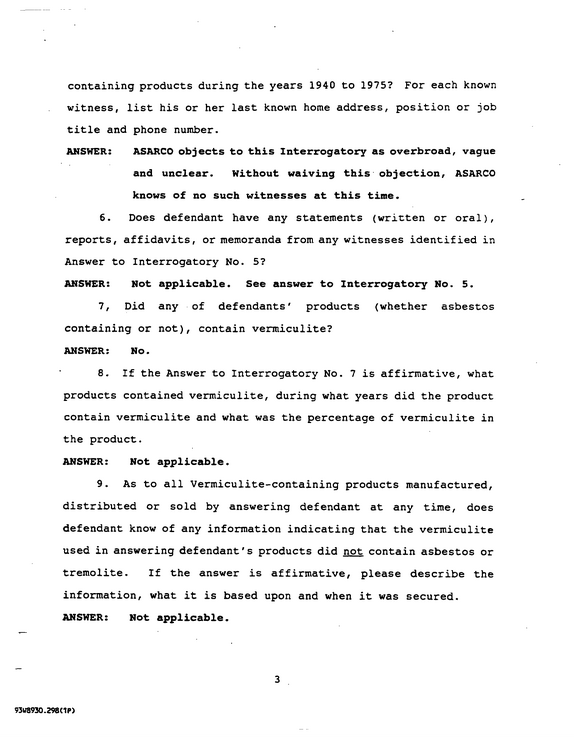
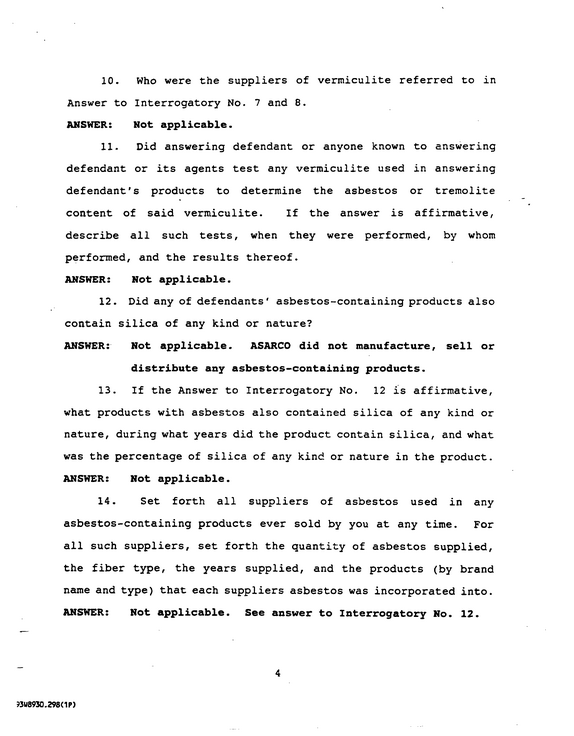
refid# n94jQryRb8Ba34BJgMpkyYQDX7 pages
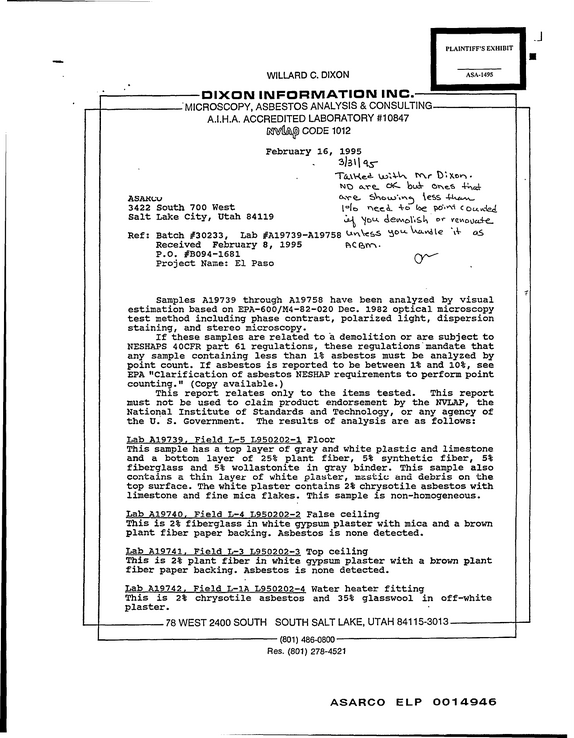
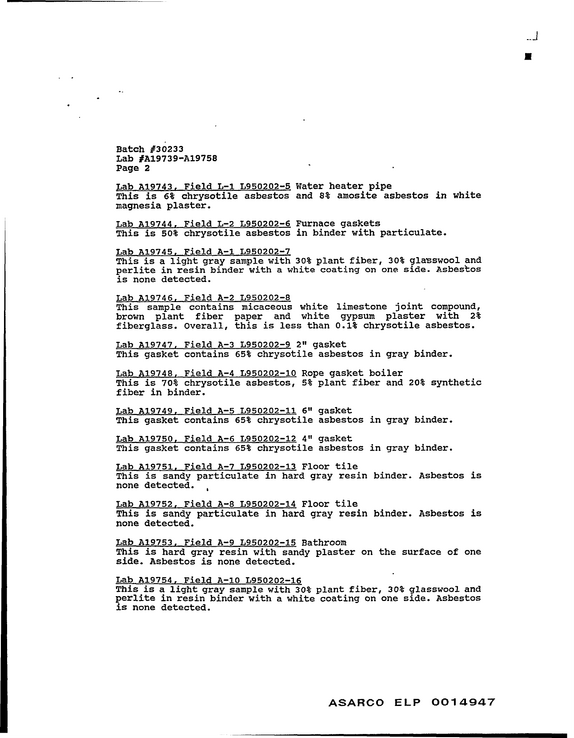
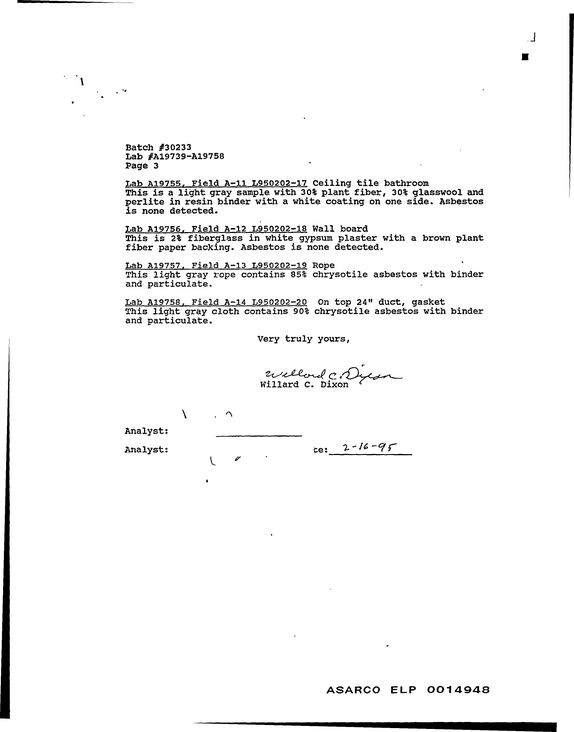
PLAINTIFF'S EXHIBIT J WILLARD C.
refid# v6wo1xQYeqLO8NqVzE0Lkn11Y3 pages
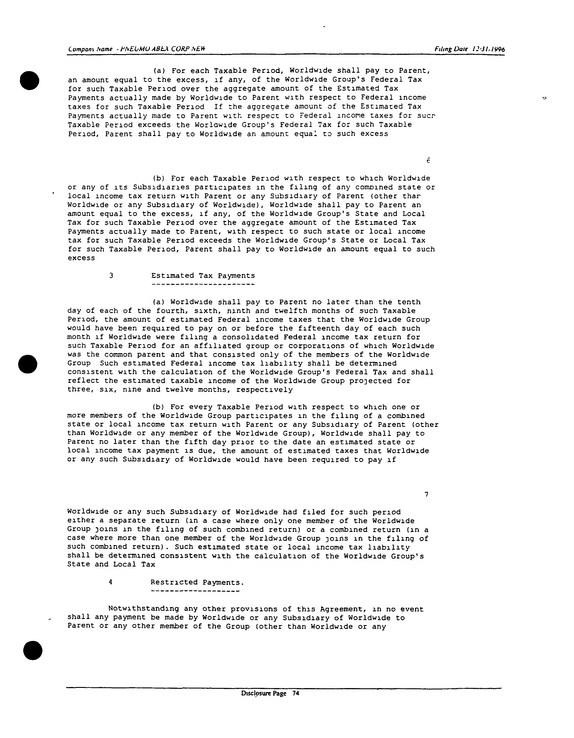
Compcm frame - PfrEbMU ABLX COUP frEH Filing Dale / J J 1,1996 (a) For each Taxable Period, Worldwide shall pay to Parent, an amount equal to the excess, if any, of the Worldwide Group's Federal Tax for such Taxable Period over the aggregate amount of the Estimated Tax Payments actually made by Worldwide to Parent with respect to Federal income taxes for such Taxable Period If the aggregate amount of the Estimated Tax Payments actually made to Parent with respect to Federal income taxes for suer Taxable Period exceeds the Worldwide Group's Federal Tax for such Taxable Period, Parent shall pay to Worldwide an amount equal to such excess (b) For each Taxable Period with respect to which Worldwide or any of its Subsidiaries participates in the filing of any comoined state or local income tax return with Parent or any Subsidiary of Parent (other thar Worldwide or any Subsidiary of Worldwide), Worldwide shall pay to Parent an amount equal to the excess, if any, of the Worldwide Group's State and Local Tax for such Taxable Period over the aggregate amount of the Estimated Tax Payments actually made to Parent, with respect to such state or local income tax for such Taxable Period exceeds the Worldwide Group's State or Local Tax for such Taxable Period, Parent shall pay to Worldwide an amount equal to such excess 3 Estimated Tax Payments (a) Worldwide shall pay to Parent no later than the tenth day of each of the fourth, sixth, ninth and twelfth months of such Taxable Period, the amount of estimated Federal income taxes that the Worldwide Group would have been required to pay on or before the fifteenth day of each such month if Worldwide were filing a consolidated Federal income tax return for such Taxable Period for an affiliated group or corporations of which Worldwide was the common parent and that consisted only of the members of the Worldwide Group Such estimated Federal income tax liability shall be determined consistent with the calculation of the Worldwide Group's Federal Tax and shall reflect the estimated taxable income of the Worldwide Group projected for three, six, nine and twelve months, respectively (b) For every Taxable Period with respect to which one or more members of the Worldwide Group participates m the filing of a combined state or local income tax return with Parent or any Subsidiary of Parent (other than Worldwide or any member of the Worldwide Group), Worldwide shall pay to Parent no later than the fifth day prior to the date an estimated state or local income tax payment is due, the amount of estimated taxes that Worldwide or any such Subsidiary of Worldwide would have been required to pay if 1 Worldwide or any such Subsidiary of Worldwide had filed for such period either a separate return (in a case where only one member of the Worldwide Group joins m the filing of such combined return) or a combined return (in a case where more than one member of the Worldwide Group joins in the filing of such combined return).
refid# gakgEM3DMapOyQ4QrvpRjao6e1 page
MAFCO CONSOLIDATED GROUP INC (Form: 10-K, Received: 03/28/1997 00 00 0 .Page 43 of 116 TAX SHARING AGREEMENT The Company and certain of its domestic subsidiaries (including Consolidated Cigar) (the "Company Group") have been, for federal income tax purposes, members of an affiliated group of corporations of which Mafco Holdings is the common parent (the "Mafco Holdings Group") Accordingly, the Company Group has been included in the consolidated federal income tax returns and, to the extent permitted by applicable law, included in combined state or local income tax returns filed on behalf of the old Mafco Holdings Group Pursuant to a tax sharing agreement (the "Mafco Consolidated Tax Sharing Agreement") between the Company and Mafco Holdings, the Company is required to pay to Mafco Holdmgs with respect to each taxable year an amount equal to the consolidated federal and state and local income taxes that would have been incurred by the Company Group had it not been included in the consolidated federal and any combmed state or local income tax returns filed by the Mafco Holdings Group Pursuant to a tax sharing agreement (the "Subsidiary Tax Sharing Agreement") between the Company and Consolidated Cigar, Consolidated Cigar is required to pay to the Company with respect to each taxable year an amount equal to the consolidated federal and state and local income taxes that would have been incurred by Consolidated Cigar had it not been included in the consolidated federal and any combined state or local mcome tax returns filed by the Mafco Holdings Group.
refid# RjMevXGwnp6g9D82eEKdOzD0k1 page
offence, the dirtying or the nuisance results from direct throwing or discharging, but also when such effect occurs indirectly, e g due to the place where the waste was disposed of, as in the case of contamination of underground aquifers " Id at 12 The Professor fails to cite any evidence indicating that contamination of the water supply occurred here Besides a lack of legal and factual support, his argument fails in light of the conclusion m the PAR report fFN121 that "the water quality is acceptable" and on account of the September 8, 1993 statement by the Province m its official chronology that the analyses done on September 7, 1992 by the Local Health Units show no contamination ofthe water inside the Orzmuovi plant See Pis ' Ex W, Tosato Rpt, p 9 FN12 The "PAR report" refers to the report prepared by PAR Sri, the consulting firm hired by Rutgers to conduct environmental inspections at the Orzmuovi plant See Defs ' Ex 52, p 3 Based on the record in this case, the Court concludes that Frendo was not m violation of article 674 of the Italian Penal Code during the relevant time periods 1FN131 FN13.The maximum punishment for violation of article 674 is one month imprisonment or a $235 fine See Pis'Ex W, Tosato Rpt, p 10 The Court therefore makes the same observation with respect to article 674 as it did with respect to article 216 of the CHA, namely, that any violation of either article would not have had a material and adverse affect on Frendo's business (finances or operations), and thus, under the terms of the 1989 Purchase Agreement, no breach of warranty would have resulted 2 Articles 440 and 452 Professor Amendola also concludes that the presence of landfills at the Orzmuovi plant violated articles 440 and 452 of the Penal Code as a result of the contamination of the aquifers Article 440, read in conjunction with article 452, relates to the negligent "adulteration or counterfeiting of edibles" and "punishes whomever corrupts water or food designated for consumption in a way that is dangerous for public health " Pis ' Ex W, Tosato Rpt ,p 11, see also Coccia Decl, Tabs 17, 18 (English translations of articles 440 Page 14 and 452) For these provisions to apply here, Plaintiffs must prove that because of the Orzmuovi landfills an adulteration of water designated for drinking occurred to such a degree as to be dangerous for public health See Pis' Ex W, Tosato Rpt, p 11 Professor Amendola, however, fails to provide any factual basis to support his conclusion As discussed in connection with Plaintiffs' article 674 claim, the record reflects that no contamination of drinking water was shown to have occurred as a result of the landfills See Roberts Aff 3, Ex B, p 152 Trying to dodge this deficiency, Professor Amendola cites a Court ofCassation decision (Criminal Division, Decision no 968, Oct 24, 1991) for the proposition that adulteration of water, pursuant to articles 440 and 452, occurs based on the mere danger ofadulteration, even ifno actual damage occurs See Pis' Ex U, Amendola Rpt, p 12 Professor Amendola has misconstrued that decision, as it held that with respect to the crime of adulteration of water, the government need not prove actual damages, provided that there is adequate evidence to establish an actual adulteration of drinkable water and a danger to public health See Pis' Ex W, Tosato Rpt, p 11 *19 Accordingly, based on the record in this case, the Court concludes that Frendo did not violate article 440 or 452 of the Penal Code 3 Article 635 In his report.
refid# aJv5MXeL3QNRgwM6baoqDgY7X1 page
a monthly publication June 30,1998 OSHA'S AMENDMENTS TO ASBESTOS STANDARDS REMOVES ROOFING SEALANTS FROM REGULATORY REQUIREMENTS As reported (N&N July & Nov. 1997), in a unanimous opinion dated July 24,1997, the U.S.
refid# gaw9zGreLMNYjakrYJa7ovp6Q4 pages
TKI.KP1 lONF. (203!
refid# baNOQjxNLMjqmyxv3jBL60xGy349 pages
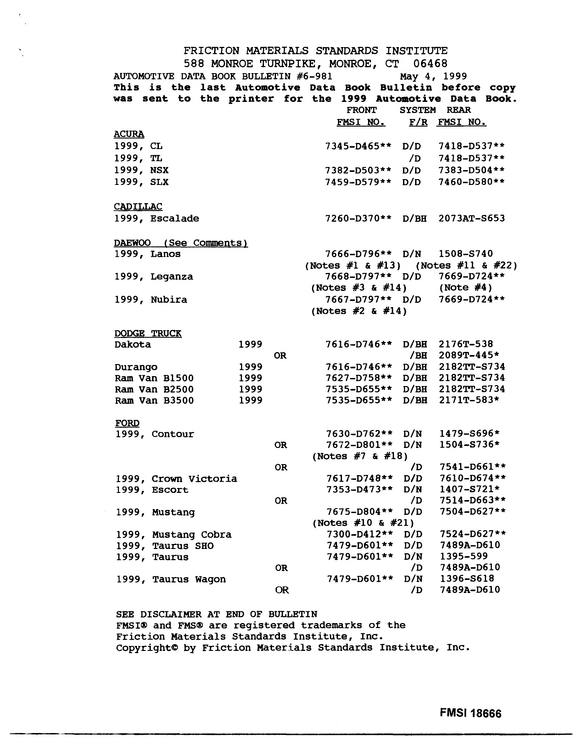
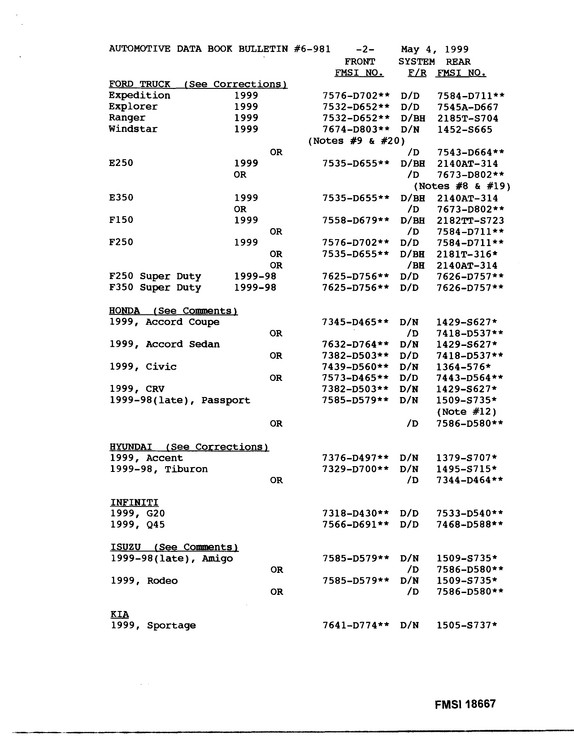
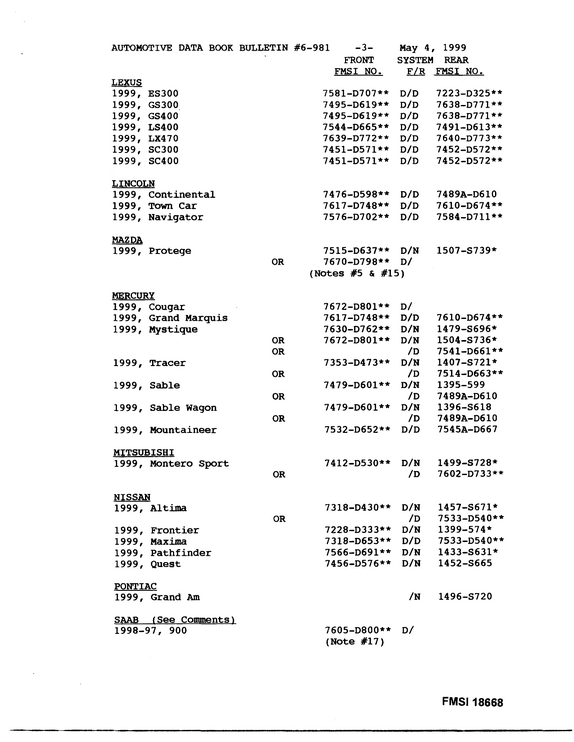
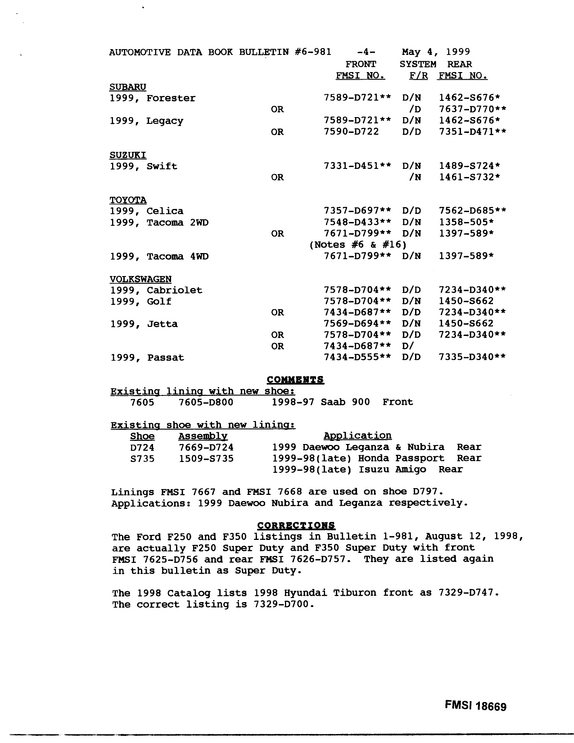
FRICTION MATERIALS STANDARDS INSTITUTE 588 MONROE TURNPIKE, MONROE, CT 06468 AUTOMOTIVE DATA BOOK BULLETIN #6-981 May 4, 1999 This is the last Automotive Data Book Bulletin before copy was sent to the printer for the 1999 Automotive Data Book.
refid# 10YY15eDa2GNMde2KX0N5d26K8 pages
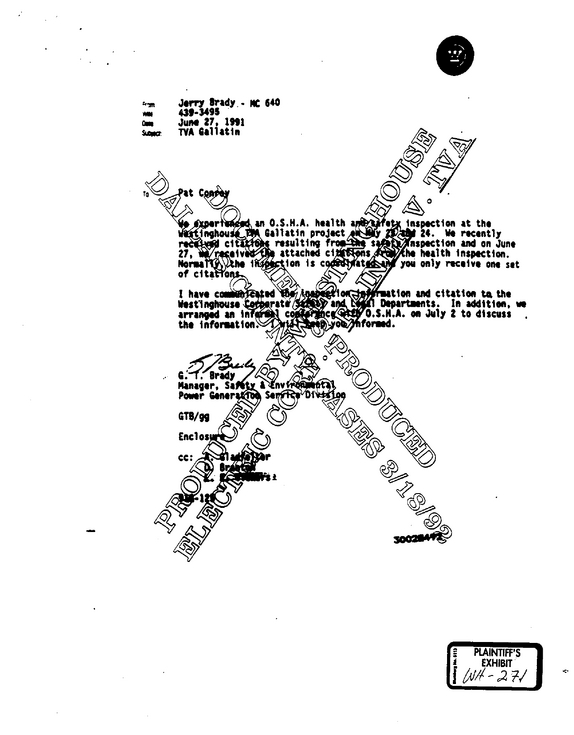
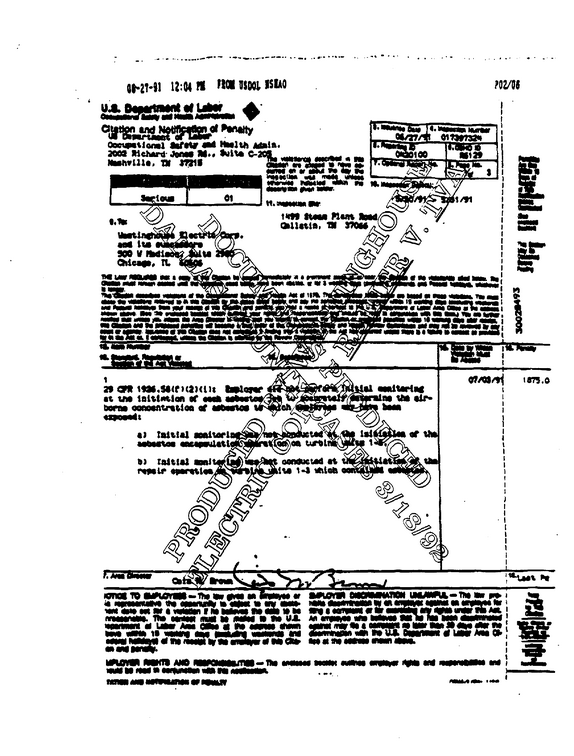
Jerry irady .
refid# oywOyEoDjMB9Q8NB0nG0OYzg6 pages
f Picillo Bromberg Caruso 1 -*11insellor* at Law Martin G.
refid# jNmLXvpYyvaybEBo0J56Y6md966 pages
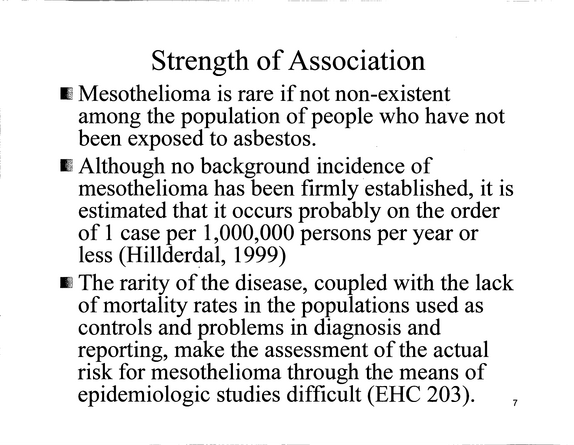
Strength of Association i Mesothelioma is rare if not non-existent among the population of people who have not been exposed to asbestos. i Although no background incidence of mesothelioma has been firmly established, it is estimated that it occurs probably on the order of 1 case per 1,000,000 persons per year or less (Hillderdal, 1999) i The rarity of the disease, coupled with the lack of mortality rates in the populations used as controls and problems in diagnosis and reporting, make the assessment of the actual risk for mesothelioma through the means of epidemiologic studies difficult (EHC 203).
refid# 3JmwYx5bLkDG0XgEYROM0GZQO1 page
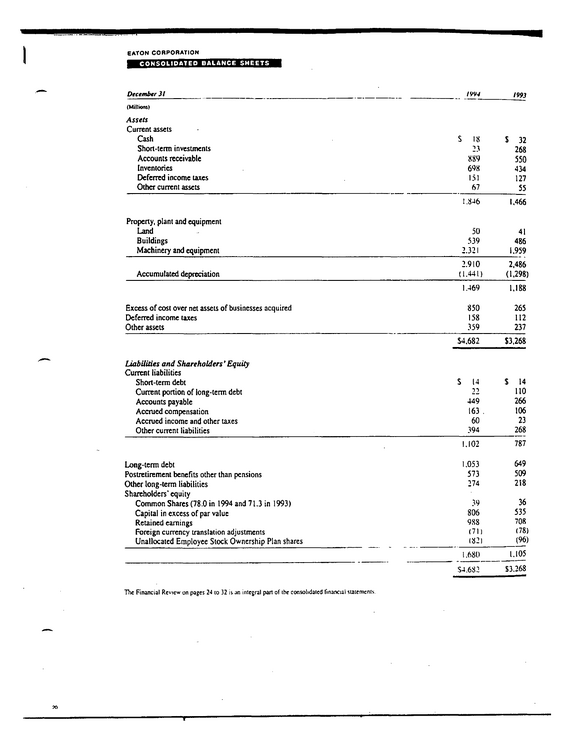
EATON CORPORATION CONSOLIDATED BALANCE SHEETS December 3t (Millions) Assets Current assets Cash Short-term investments Accounts receivable Inventories Deferred income taxes Other current assets Property, plant and equipment Land Buildings Machinery and equipment Accumulated depreciation Excess of cost over net assets of businesses acquired Deferred income taxes Other assets Liabilities and Shareholders' Equity Current liabilities Short-term debt Current portion of long-term debt Accounts payable Accrued compensation Accrued income and other taxes Other current liabilities Long-term debt Postretiremen!
refid# jNVGwMwjDJZ80grMdwayxwQ1Z1 page
Eaton Corporation Report of Management We have prepared the accompanying consolidated financial statements and related information included herein for each of the three years in the period ended December 31.1997.
refid# kmdxV0Kj1b94VXVq4vqowvzkV1 page