Refine
Estimated Years 1970-1979Clear
27,937 results foundRefine Search
EARLAND E.
refid# X7dMO57EVd8v1g64ON2DY3VKK1 page
t=^ V.
refid# Jrm3DBOrED3g7mZXvo0pyRzNv2 pages
Vo1- 291 No. 11 CORRESPONDENCE 583 Latin square.
refid# bOYdj8M2Dvy7dQQDX7OjJQYw02 pages
Comments of Johns-SVlanvillle Corporation with respect to____ Notice of Proposed Rulemaking .
refid# 7MrDjrvv4kXpGdO32j8dJG4VE34 pages
DUST EXPOSURES DURING THE CUTTING AND MACHINING OF ASBESTOS/CEMENT PIPE ADDITIONAL STUDIES Prepared for The A/C Pipe Producers Association 1600 Wilson Boulevard Suite :308 Arlington, Virginia 22209 Prepared by Equitable Environmental Health, Inc. 2020 Mil via Street Berkeley, California 94704 December 15, 1977 SC-JMM-1875 BEN 0004805 INTRODUCTION On March 16, 1977, Equitable Environmental Health, Inc., submitted a draft report to the A/C Pipe Producers Association which provided quantitative data on dust exposures during field operations in which sewer and pressure pipe were subjected to a number of typical field cutting and machining operations.
refid# 7Z4vEk71aBKKkYagEO9D35rg40 pages
QlsoO ..
refid# mBNj5exX2NgRVJ9Z8Xz2gBBmZ1 page
Faco Textures Corporation 10*7 C OMH E H C lA L OTAEET SAN CARIOS, CALIFORNIA *4070 14 11)1*1.0*11 November $, 1973 Rhoda E.
refid# XOoYE0dDQZg9mQeep1ONbwVXG1 page
PLAINTIFF'S txiuuir KM-132 PACO TEXTURES MEMO TO: Frank Scaggs FROM: Doug Merrill SUBJECT: MON-ASBESTOS CEILING TEXTURE October 8, 1976 Even though the state agencies in the Northwest have not taken a strong stand on asbestos, I'm sure the day will come.
refid# O13OJN2keMjeOj8e2GQ5aqZoX2 pages
(NOUSTWlAL HEALTH FOUNDATION.
refid# 5DM4nznwnkGE2VZoabBLeGKzD1 page
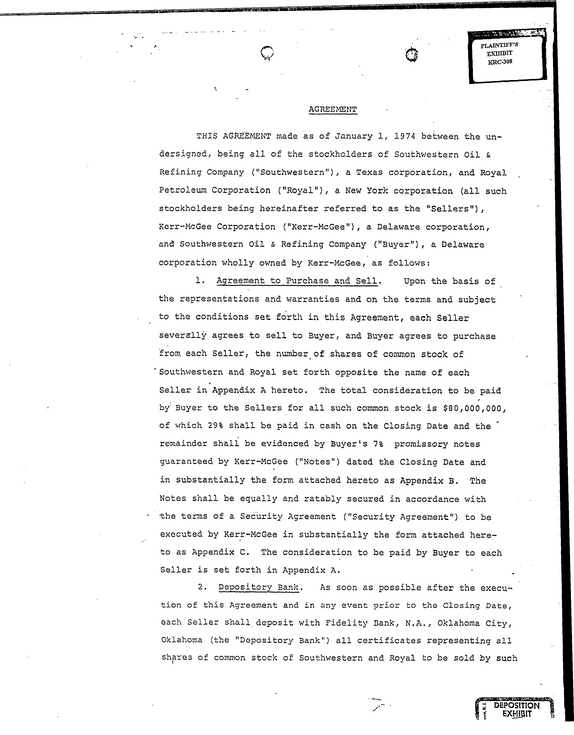
AGREEMENT THIS AGREEMENT made as of January 1, 1974 between the un dersigned, being all of the stockholders of Southwestern Oil & Refining Company ("Southwestern"), a Texas corporation, and Royal Petroleum Corporation ("Royal"), a New York corporation (all such stockholders being hereinafter referred to as the "Sellers"), Kerr-McGee Corporation ("Kerr-McGee"), a Delaware corporation, and Southwestern Oil & Refining Company ("Buyer"), a Delaware corporation wholly owned by Kerr-McGee, as follows: 1.
refid# OJ49rKbxjVzNgqkRp10KwX8pX54 pages
Pacific Asbestos Corporation COPPEROPOLIS, CALIFORNIA 95228 TELEPHONE 209/78S-220I TLX 3S94S8 CABLE ADDRESS CHBYSOTILE Pacific Asbestos Corporation April 11, 1972 Mr.
refid# y5v7L8O82DDMxqQ6w0706mZ42 pages
r TECHNICAL BULLETIN f'fr/^te^ns!
refid# kmGryYx1bbo05GwmrRLzJw8RV2 pages
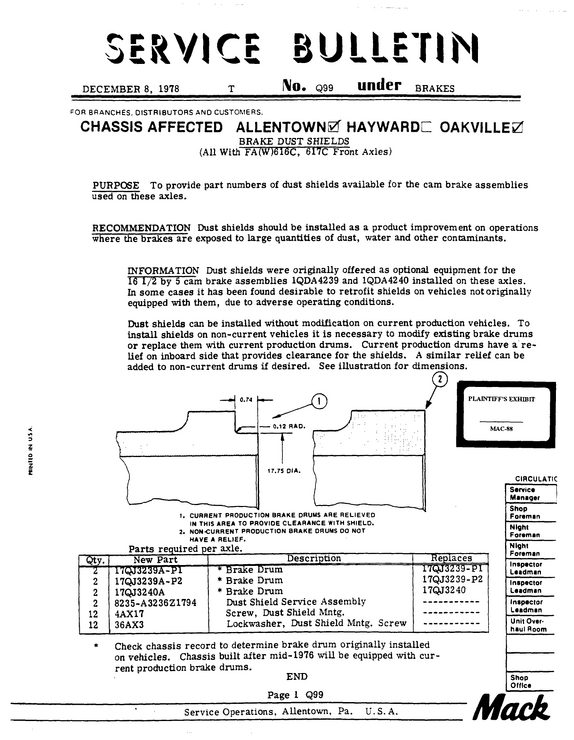
SERVICE BULLETIN DECEMBER 8, 1978 T___ No.
refid# rBJQ76ZyDVemq42gJ9nyQkoKr1 page
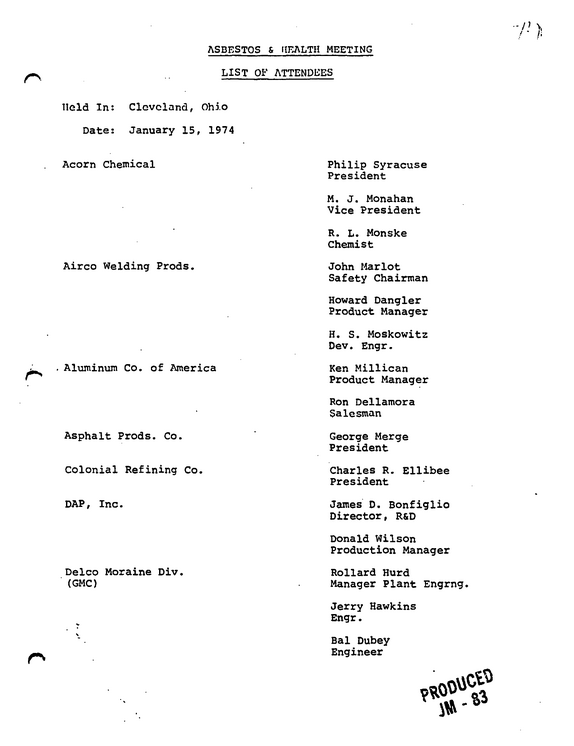
ASBESTOS & HEALTH MEETING LIST OF ATTENDEES Held In: Cleveland, Ohio Date: January 15, 1974 Acorn Chemical Airco Welding Prods. .
refid# VgxRjd3ox82mNEgRYLvR6XKo1 page
cent, stock insurers have steadily increased their proportion of the business Self-insurers In all jurisdictions (except Nevada, North Dakota, Puerto Rico, Texas, the Virgin Islands, and Wyoming), employers are permitted un der certain conditions to self-insure workmen's compensation Although most jurisdictions re ported 200 or fewer self-insurers, self-insured employers in 1970 paid 14 I percent of the workmen's compensation benefits Self-insurance is becoming popular among those who qualify In 1960 self-insurers paid only 12 4 percent of the benefits Most states report an increase also in the number of selfinsurers Possible explanations are increasing cost consciousness, sales activities of agencies who seek to manage self-insurance programs, and the business merger movement which in creases the size of firms and their ability to self-insure Self-insurance is attractive primarily because it may be less costly than insurance An in surance premium is designed to pay the losses and expenses of the insurer and provide a margin for profit or contingencies The selfinsurer hopes to save money on the loss or the expense and profit components of the pre mium The loss component equals the average loss the insurer expects the employer and others like him to experience If the employer is so much better than the average employer in his class that his expected loss may be less, he would save money by self-insunng In the short run, however, the loss experience may differ substantially from the expected loss Indeed the loss m a single year might be cata strophic The larger the number of em ployees, the less the nsk of fluctuation in annual losses For most employers, the nsk is such that self-insurance is out of the ques tion For others, the comparison between actual and expected loss is an important con sideration By self-insunng, the employer can save that part of the premium charged to cover selling expenses, some general administration ex penses, and profits There may also be savings on loss prevention and loss adjustment services even though these services must still be performed Other considerations include the relative quality of the safety and claims services pro vided by insurers, by management service organizations, and by employers themselves, by tax factors, and by the opportunity cost of paying an insurer a premium instead of pay ing losses and expenses as they occur Cost Levels and Allocation Workmen's compensation costs and other costs of industrial accidents impose a burden on industry, workers, and society generally The magnitude of these costs and their dis tribution have important economic implica tions and pose several critical issues of policy.
refid# e7oyzgnyQq4E1RV77Y5dndEaM1 page