Refine
Estimated Years 1990-1999Clear
5,222 results foundRefine Search
3 i^o%o IN THE CIRCUIT COURT OF KANAWHA COUNTY STATE OF WEST VIRGINIA RE: ASBESTOS W.V.
refid# wKRjbdMeLVmjynaNB5oZOZGV79 pages
RISK ENGINEERING June 9, 1997 ZURICH SERVICES CORPORATION PLAINTIFF'S EXHIBIT H&G-58 Brad Heath Plant Manager Hill and Griffith Company 4606 W. 16th Street Cicero, Illinois 60804 l Report for Industrial Hygiene Services Provided on May 13, 1997 Dear Mr.
refid# wDRbpzL2BegpwrNY0pXvveg7Q1 page
AFFIDAVIT CITY OF PITTSBURGH STATE OF PENNSYLVANIA ) ss BEFORE ME, a Notary Public in and for the State of Pennsylvania personally appeared CM-- who stated under due oath of law as follows: am a librarian for the Carnegid^ibrary in Pittsburgh, Pennsylvania.
refid# dDvLQBLbE1OYy02kpMQvVg2M56 pages
Pergamon Ann. odMfi. flk, VoL 40, No. 5. pp, W3-WS, |f Copyright 1996 Bntith Oxupsuanal Hypeae Society fuhliihd by t3cericr Sdwce Lid.
refid# 4EjJppz8dv48eVZnxg9q2bEe6 pages
* PLAINTIFFS BRAYTON & ASSOC I EXH^IT 3 3 3 3r 1 WILLIAM.
refid# qX0DE0Y90pqz6ay5JG5rmVQ544 pages
f ) l 1 1 STATE OF WEST VIRGINIA 2 CIRCUIT COURT OF MONONGALIA COUNTY 3 * ****************** + ********* 4 WITNESS: ANDREW R.
refid# 2RLNvjyLM8M26pmQNnn8944r7103 pages
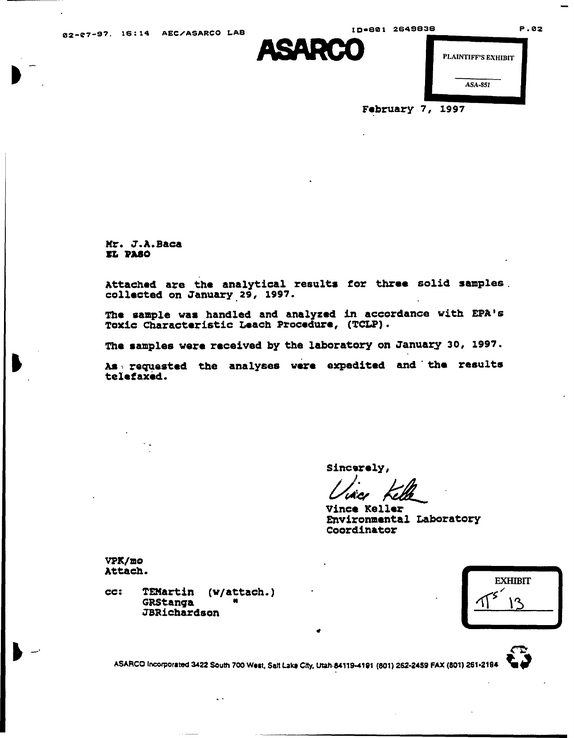
02-C7-9?.
refid# daReepnM5bZMVn77Dm5oeXB094 pages
periods ending on or before the Closing Date, (x) the provision of any receipts evidencing the payment of Taxes as may be re quired by Seller to substantiate any claim for tax credits, (y) with respect to periods beginning before and ending on or after the Closing Date, the provision by Buyer to Seller within ninety (90) days after the Closing Date of (i) Seller's 1994 federal and state tax information packages prepared in a manner consistent with the packages customarily prepared for periods ending prior to the Closing with respect to the Division and (ii) the tax information package supplied to Buyer by Seller or its representative with respect to the Canadian Subsidiary completed in a manner consistent with prior years returns, and U) the grant of authority with respect to the Canadian Sub sidiary, by means of a power of attorney or otherwise, to an officer or other representative of Seller to sign and file Returns and defend audits (on behalf of the Canadian Subsid iary) or reasonably necessary to enable the Seller to satisfy its obligations to provide such information and assistance under the Whitman Agreements; (ii) retain for the statute of limitations period (including any extensions) applicable with ; respect to such returns, audits, examinations, or proceedings, such material records or information as may be relevant there to; (iii) provide the other party with reasonable access to, and allow the other party to make copies and extracts of, such records or information, and prior to disposing of any such records or information allow the other party (at the possessing ; party's cost and expense of shipping) the right to obtain the originals of such records or information; (iv) in connection with such returns, audits, examinations, and proceedings, cause its relevant employees and representatives to be reasonably available to the other party and to provide to the other party reasonable technical support (including, without limitation, f the provision of interpretations, analyses, and testimony with respect to inventory, contract backlog orders, engineering drawings, software, and other intangibles); and (v) provide the other party with any final determination of any such audit, examination, or proceeding that affects the amount required to be shown on any tax return of the other party for any period. 1 The party requiring assistance shall reimburse the other party for all reasonable out-of-pocket costs incurred as a direct result thereof (excluding costs of time expended by employees).
refid# g2QKmojqZd2Ev25V0LooNz2G1 page
April 3, 1990 Ashcraft & Gerel 2000 L Street N.W.
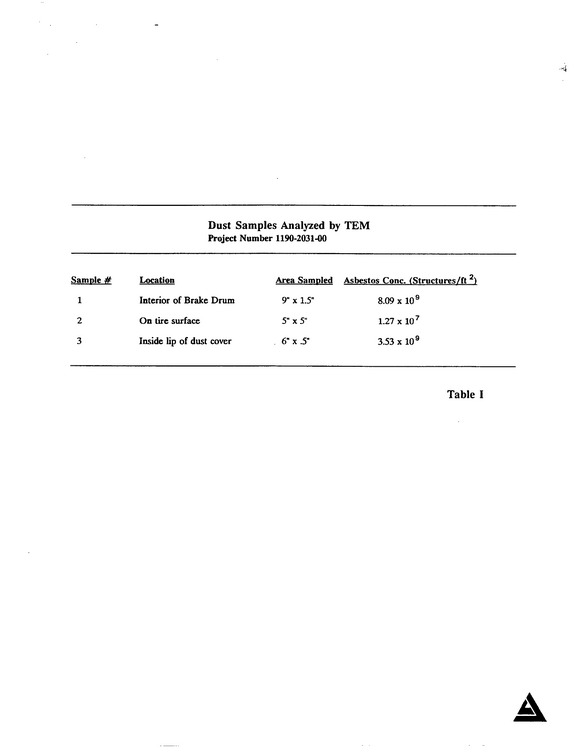
refid# G6LMmRNw3rJakDVOYELGaYYMv15 pages
"Current U.S.
refid# 9XmEyw7zX806MKV9L5R1jBk31 page
MAFCO CONSOLIDATED GROUP INC (Form 10-K, Received: 03/28/1997 00.00 00) Page 9 of 116 has taken, and will continue to take, action to protect its interests in all such trademarks. 7 RAW MATERIALS The Company has developed and is developmg long-term relationships with tobacco suppliers and is expanding its commercial and technical ties with local growers to secure a variety of sources for raw materials, ensure the quality of its raw materials and maximize cost savings The Company buys tobacco directly from a large number of suppliers in Brazil, Cameroon, the Central African Republic, Costa Rica, Germany, Italy, the Dominican Republic, Paraguay, the Philippines, Indonesia, the United States, Ecuador, Honduras, Mexico and other countries and does not believe that it is dependent on any single source for tobacco.
refid# oe0o6mx4VRw5zkakz4kxrRbxR1 page
MAFCO CONSOLIDATED GROUP INC (Form: 10-K, Received: 03/28/1997 00:00:0 .
refid# evd153qkRM0dL5gbzY4Zg5X1E1 page
PURCHASE AND SALE AGREEMENT BETWEEN COOPER INDUSTRIES, INC AND FEDERAL-MOGUL CORPORATION DATED AUGUST 17,1998 (j) Neither Seller nor any Champion Company has engaged in any transaction with respect to any Benefit Plan which may result in the imposition on Seller or any Champion Company of any excise tax under Sections 4971, 4972, 4975, and 4976 through 4980 of the Code, or otherwise incurred a liability for any excise tax, other than excise taxes which have heretofore been paid or have been accrued, and, in either case are fully reflected in the Financial Statement, and neither Seller nor any Champion Company is now, nor at any time will be by virtue of any action taken prior to the Closing Date, subject to a requirement to provide security under Section 401(a)(29) of the Code, nor shall any asset of Seller or any Champion Company be subject to a lien by reason ofthe provisions of Section 412(n) of the Code.
refid# 6BVneYqNOy91VGB6qMO6DMXY41 page
EXHIBIT I CERTAIN DEFINITIONS "Abex Products" has the meaning set forth in Section 5.25.
refid# GmYwKkzQK4pZw0B0GXekOKbm41 page
finds that this application satisfies the notice requirement under article 216 of the CHA *17 Article 216's location requirement provides that a manufacturing facility must be located in the countryside and removed from any housing, or, if located in an inhabited area, the facility must not create a public health risk See Coccia Decl, Tab 12 With regard to this requirement, the Court observes that, given the evidence in this case, including pictures ofthe Orzinuovi plant, the facility appears to be situated in an uninhabited area, which means that article 216 imposes no further obligation on the operator of this facility See, eg, Pis ' Summary Judgmt Br,Ex A Moreover, Plaintiffs fail to point to evidence that suggests otherwise But even assuming that the Orzinuovi plant is located within an inhabited area, the facility was not out of compliance with the CHA This is true on account of the pronouncement m the Mayor's January 23,1993 order, issued pursuant to the CHA, stating that the Orzinuovi plant posed no public health risk IFNI 11 Other factors lend support to this conclusion, including the opinion ofPlaintiffs' own environmental consultant, who advised Plaintiffs' lawyers that any pollution caused by the landfills appeared to be contained within the plant and that the conditions in the surrounding area were acceptable See Defs ' Ex 52, p 5 FN11 For this reason, article 217 of the CHA was not violated either, since the Mayor has authority to act under this article only when operation of a given facility creates a specific danger for public health See Pis' Ex.
refid# zz833kRwLavp0Zqz1EVYgKLyg1 page