Refine
Estimated Years 2000-2009Clear
6,589 results foundRefine Search
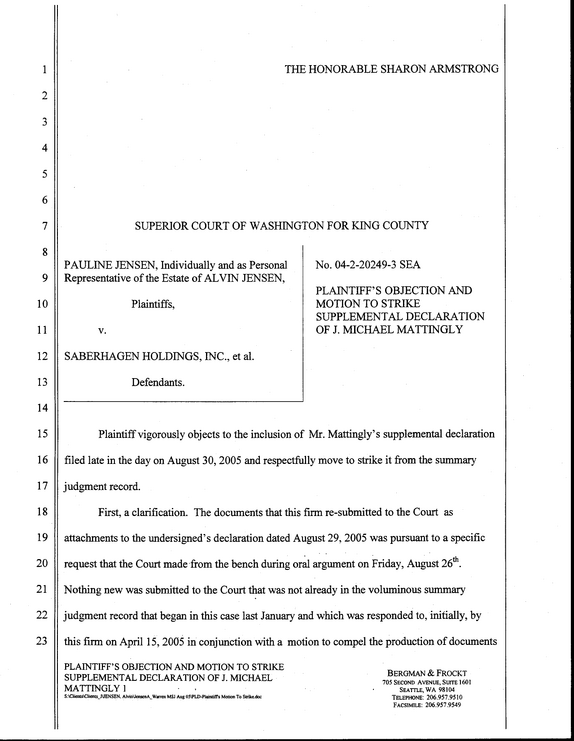
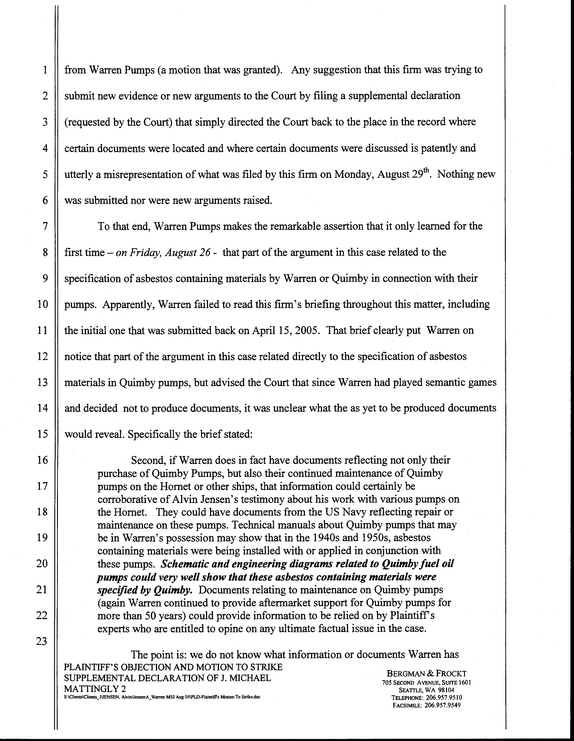
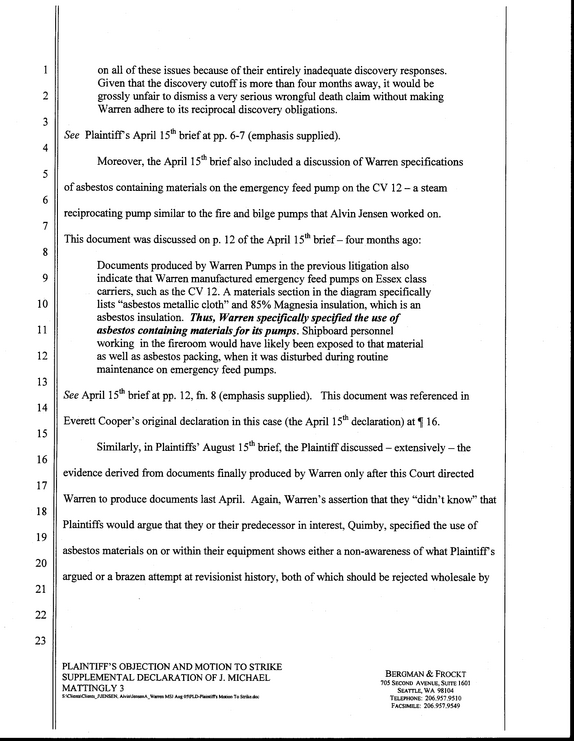
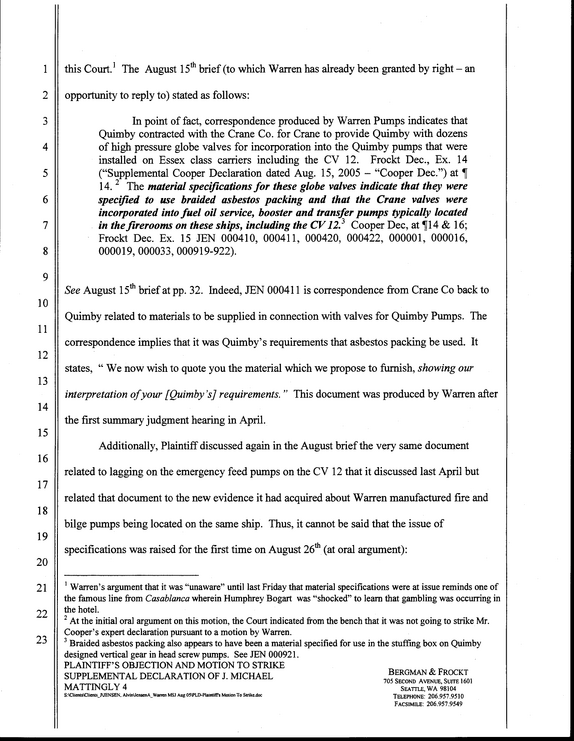
1 THE HONORABLE SHARON ARMSTRONG 2 3 4 5 6 7 SUPERIOR COURT OF WASHINGTON FOR KING COUNTY 8 PAULINE JENSEN, Individually and as Personal 9 Representative of the Estate of ALVIN JENSEN, 10 Plaintiffs, 11 v.
refid# 6bqKvJvNRrvKGELJoQYx0gyNE19 pages
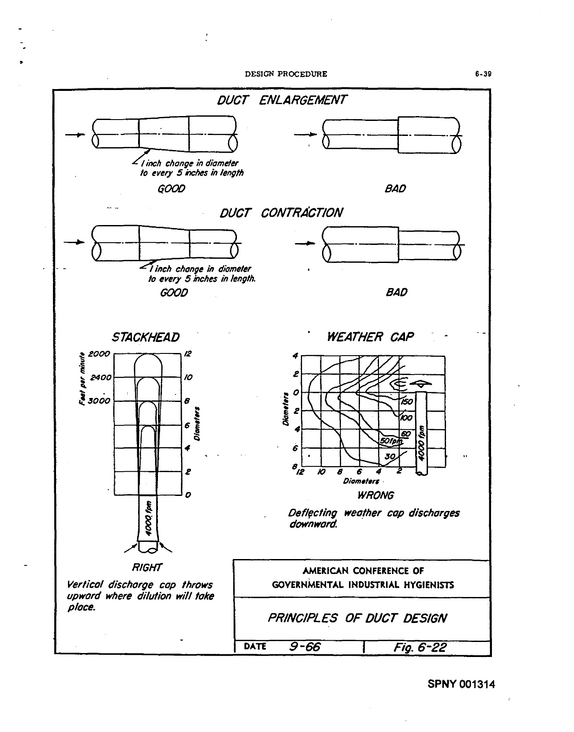
DESIGN PROCEDURE DUCT ENLARGEMENT / inch change in diameter to every 5 inches in length GOOD DUCT CONTRACTION BAD 6-39 l inch change in diameter to every 5 inches in length.
refid# 6wz10pdg4RLYv52M5V6LE0X4m1 page
CERTIFICATE OF SERVICE The foregoing Defendant Pneumo Abex Coiporation's Responses to Plaintiffs' Requests for Production,of Documents has been mailed by regular U.S. mail, postage prepaid, this 29th day of May, 2001* to Ladd R.
refid# OzOe3djM5vNxx6w3z22EJvgLX1 page
United States Patent 4,240,530 Page 5 of 6 The calotte-shaped embossings 7 and 8 in parts 3 and 2, respectively, are axially aligned.
refid# NNekdnmO1Y83Vzz1Lk9EX5QOE1 page
p - ticket THE BENDIX CORPORATION FRICTION MATERIALS DIVISION TROY, NEW YORK CLEVELAND,TENN.
refid# r6kyGOzeGZXMzoBbMYYgxm5qr1 page
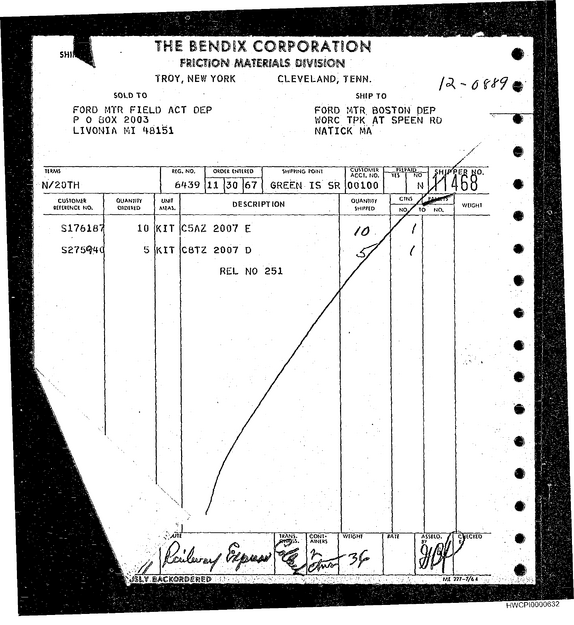
THE BEND1X CORPORATION SHI: FRICTION-MATERIALS DIVISION ' TROY, NEW YORK SOLD TO CLEVELAND,TENN.
refid# gDLqq7nmLmgja55xxo3366e3V1 page
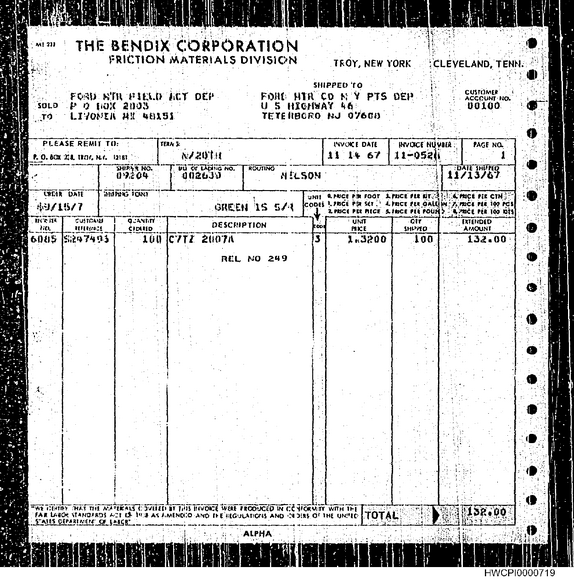
M: J3I f-.V THE BENDIX CORPORATION FRICTION MATERIALS DIVISION TROY, NEW YORK *m iull.d litr ots* SOLO .p 0 fiOX 2t103 ,T5 U'VOtoJl Ml 4HX31 SHIPPED ro FOiU Mlft" CO M V PTS DEI* U S HIGHWAY TETEItBCRO NJ 07600 :CLEVELAND, TENH.
refid# rxoJYBbNYbwEEvaB1Ew54mBNJ1 page
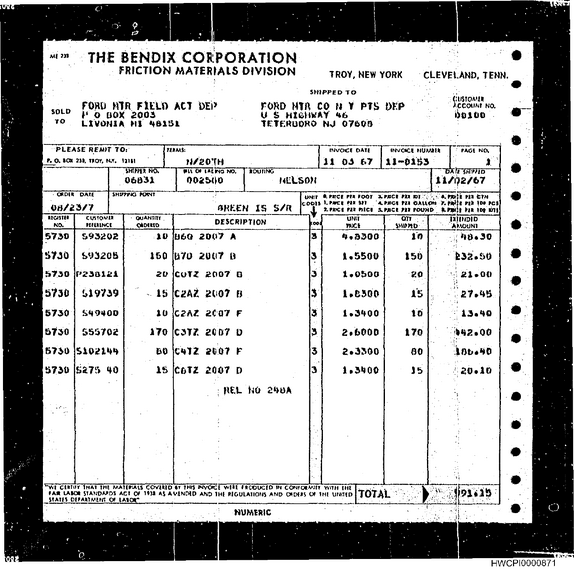
*" THE BENDIX CORPORATION FRICTION MATERIALS DIVISION TROY, NEW YORK fOBO MTR FIELD ACT DEl> SOLO 1` o BOX 2003 TO LIVONIA Ml *48151 SHIPPED TO FORD MTft CO N Y PTS DK'P U S HIGHWAY 46 TtTKRUORO NJ 07600 CLEVELAND, TENN.
refid# 6RzQg7moR0KOd0EEYvpj80NRd1 page
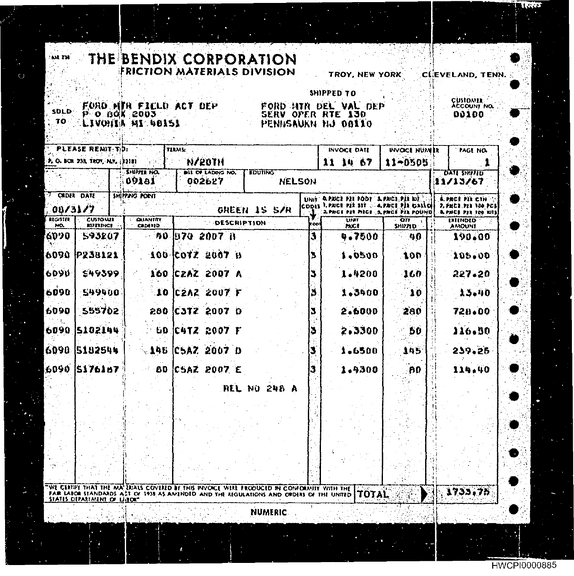
Ml tU BEND1X CORPORATION FRICTION MATERIALS DIVISION TROY.
refid# 9Ja81NevZD1KXGLkn2QXb11qe1 page
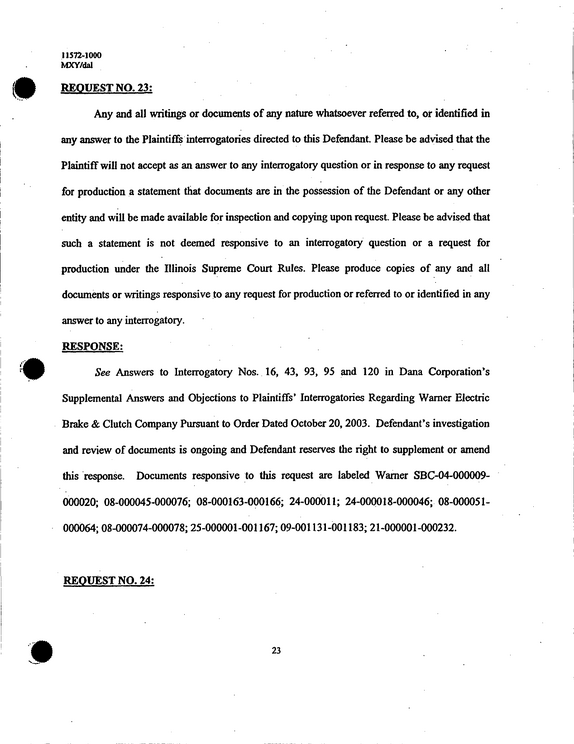
11572-1000 MXY/dal REQUEST NO. 23: Any and all writings or documents of any nature whatsoever referred to, or identified in any answer to the Plaintiffs interrogatories directed to this Defendant.
refid# EdeYQxX3qM8Q9DbywyGLpoyQb1 page
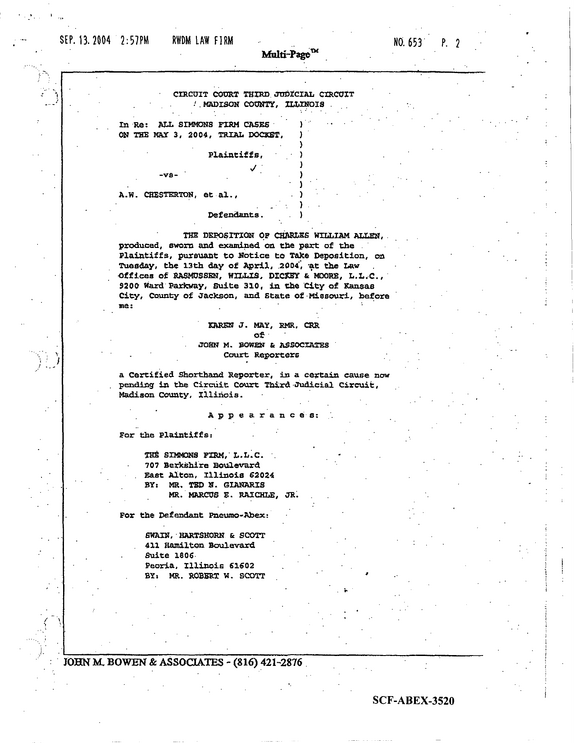
SEP. 13.2004 2:57PM RWDM LAW FIRM Multi-PageTM NO. 653 P. 2 CIRCUIT COURT THIRD JUDICIAL CIRCUIT ' .
refid# X8wJVQ0qdOXDQBxMVQQ233EJR1 page
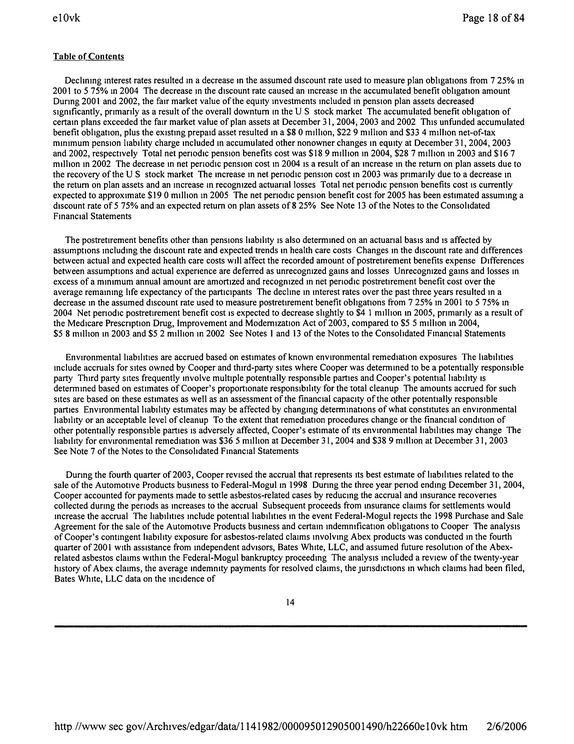
elOvk Page 18 of 84 Table of Contents Declining interest rates resulted in a decrease in the assumed discount rate used to measure plan obligations from 7 25% in 2001 to 5 75% in 2004 The decrease in the discount rate caused an increase in the accumulated benefit obligation amount During 2001 and 2002, the fair market value of the equity investments included in pension plan assets decreased significantly, primarily as a result of the overall downturn in the U S stock market The accumulated benefit obligation of certain plans exceeded the fair market value of plan assets at December 31,2004, 2003 and 2002 This unfunded accumulated benefit obligation, plus the existing prepaid asset resulted in a $8 0 million, $22 9 million and $33 4 million net-of-tax minimum pension liability charge included in accumulated other nonowner changes in equity at December 31,2004, 2003 and 2002, respectively Total net periodic pension benefits cost was $18 9 million in 2004, $28 7 million in 2003 and $16 7 million in 2002 The decrease in net periodic pension cost in 2004 is a result of an increase in the return on plan assets due to the recovery of the U S stock market The increase in net periodic pension cost in 2003 was primarily due to a decrease in the return on plan assets and an increase in recognized actuarial losses Total net periodic pension benefits cost is currently expected to approximate $19 0 million in 2005 The net periodic pension benefit cost for 2005 has been estimated assuming a discount rate of 5 75% and an expected return on plan assets of 8 25% See Note 13 of the Notes to the Consolidated Financial Statements The postretirement benefits other than pensions liability is also determined on an actuarial basis and is affected by assumptions including the discount rate and expected trends in health care costs Changes in the discount rate and differences between actual and expected health care costs will affect the recorded amount of postretirement benefits expense Differences between assumptions and actual experience are deferred as unrecognized gams and losses Unrecognized gams and losses in excess of a minimum annual amount are amortized and recognized in net periodic postretirement benefit cost over the average remaining life expectancy of the participants The decline in interest rates over the past three years resulted in a decrease m the assumed discount rate used to measure postretirement benefit obligations from 7 25% in 2001 to 5 75% m 2004 Net periodic postretirement benefit cost is expected to decrease slightly to $4 1 million in 2005, primarily as a result of the Medicare Prescription Drug, Improvement and Modernization Act of 2003, compared to $5 5 million m 2004, $5 8 million in 2003 and $5 2 million in 2002 See Notes 1 and 13 of the Notes to the Consolidated Financial Statements Environmental liabilities are accrued based on estimates of known environmental remediation exposures The liabilities include accruals for sites owned by Cooper and third-party sites where Cooper was determined to be a potentially responsible party Third party sites frequently involve multiple potentially responsible parties and Cooper's potential liability is determined based on estimates of Cooper's proportionate responsibility for the total cleanup The amounts accrued for such sites are based on these estimates as well as an assessment of the financial capacity of the other potentially responsible parties Environmental liability estimates may be affected by changing determinations of what constitutes an environmental liability or an acceptable level of cleanup To the extent that remediation procedures change or the financial condition of other potentially responsible parties is adversely affected, Cooper's estimate of its environmental liabilities may change The liability for environmental remediation was $36 5 million at December 31,2004 and $38 9 million at December 31, 2003 See Note 7 of the Notes to the Consolidated Financial Statements During the fourth quarter of 2003, Cooper revised the accrual that represents its best estimate of liabilities related to the sale of the Automotive Products business to Federal-Mogul in 1998 During the three year period ending December 31, 2004, Cooper accounted for payments made to settle asbestos-related cases by reducing the accrual and insurance recoveries collected during the periods as increases to the accrual Subsequent proceeds from insurance claims for settlements would increase the accrual The liabilities include potential liabilities in the event Federal-Mogul rejects the 1998 Purchase and Sale Agreement for the sale of the Automotive Products business and certain indemnification obligations to Cooper The analysis of Cooper's contingent liability exposure for asbestos-related claims involving Abex products was conducted in the fourth quarter of 2001 with assistance from independent advisors, Bates White, LLC, and assumed future resolution of the Abexrelated asbestos claims within the Federal-Mogul bankruptcy proceeding The analysis included a review of the twenty-year history of Abex claims, the average indemnity payments for resolved claims, the jurisdictions in which claims had been filed, Bates White, LLC data on the incidence of 14 http //www sec gov/Archives/edgar/data/1141982/000095012905001490/h22660el0vk htm 2/6/2006
refid# YDo1Y763a99ao2VyNEK1emJxV1 page
elOvk Page 59 of 84 http //www.sec gov/Archives/edgar/data/1141982/000095012905001490/h22660e 10vk.htm 2/6/2006
refid# yYEbx5oQ7a57Owe1zp53rVVE1 page
ASBESTOS INFORMATION ASSOCIATION PMB 114, 1235 Jefferson Davis Highway Arlington VA Tele: (703) 560-2980 Fax (703) 560-2981 March 23, 2000 Memorandum For: Subject: AIA/NA Members AIA/NA Contributing Members Item of Interest; forwarding of Enclosed please find a packet of information that describes a new internet site dedicated to chrysotile asbestos which is now on line at www.chrysotile.com.
refid# EdGkK9vZ9Z5OrejRyX2EQ0Nrg1 page
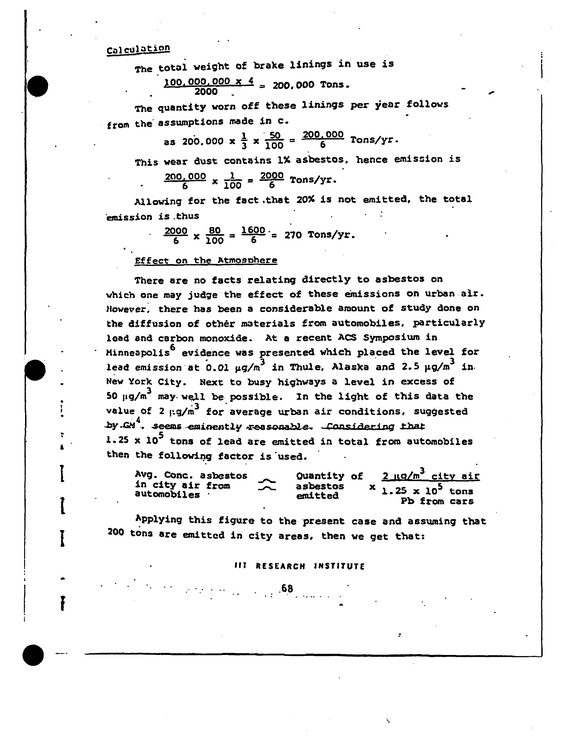
peculation The total weight of brake linings in use is 100, 000, QOQ, X _4 __ 200,000 Tons. 2000 The quantity worn off these linings per year follows from the' assumptions made in c.
refid# jm6NR8abao3ZJMjQj2Odmq5291 page